By CJ Jordan
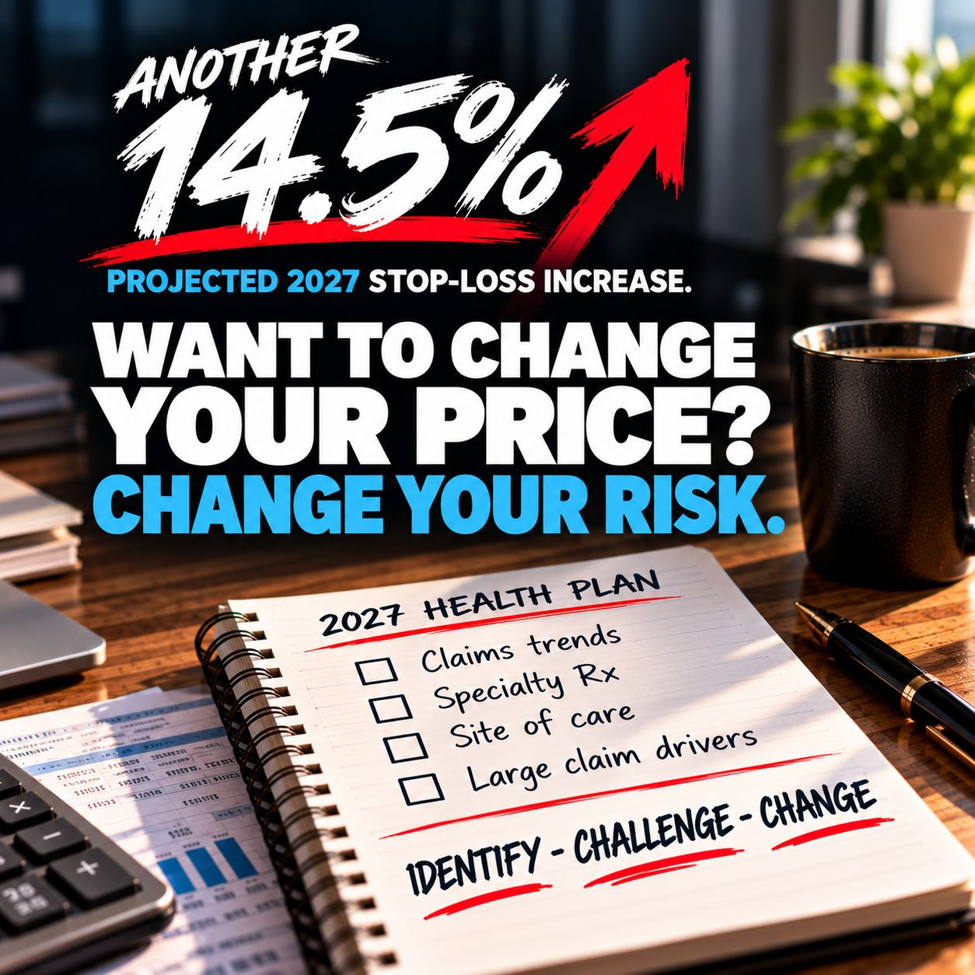
Your high stop loss renewal is a function of a bad math problem. The math doesn’t math. Let me explain.
Take one dollar of premium. Let’s say the broker gets 5 cents. Admin and premium tax take about 10. The carrier wants 10 cents of profit. That leaves 75 cents to pay claims.
In 2025, stop loss carriers paid 91 cents in claims.
The carrier is losing money on your plan. It will raise premium until the math works again. Getting back to 75 cents means about a 21% increase before medical trend is added.
Chasing a lower stop loss number doesn’t ultimately solve your problem.
Only one number in that equation is in your control. Claims.
Know who your high-cost members are before renewal. Get them to good care at a fair price. Audit your pharmacy contract. Invest in primary care.

Here’s the math illustration with the addition of medical trend and deductible leveraging:
91% loss ratio inclusive of 25% fixed costs / .75 target breakeven loss ratio = +21% = 1.21 X 9% trend = 1.32.
Specific deductible leveraging effect example:
An employer has a Specific Stop Loss deductible of $150,000 and has a $250,000 claim. Under the terms of their policy, the employer is responsible for the first $150,000, and the Stop Loss carrier reimburses the plan for the remaining $100,000. So far, so clear.
The next year, let’s assume medical costs increase by 9% and the same claim occurs again. The $250,000 claim has grown to $272,500.
Let’s see how this plays out: the employer’s claim costs are flat, but the Stop Loss carrier’s claim costs have gone up by 22.5%
One must remember that stop loss policies are pooled policies and reinsurance coverage often, if not always, plays a role in the backroom.
HOMEWORK READING ASSIGNMENT: Stop Loss Premium Survey | Aegis Risk