By Craig Gottwals – Cutting Healthcare Spend 20–40% for Lean-Margin Businesses | Attorney & RBP Expert
September 28, 2026
How a Federal Court Ruling Exposes the Structural Conflict in Bundled Health Plans
In February 2022, a baby girl was born in Idaho with serious birth defects and transferred to the newborn ICU at Lucile Packard Children’s Hospital in California.
Her parent worked for Scentsy, which ran a self-funded health plan. Blue Cross of Idaho processed the claims. Blue Cross of Idaho also sold Scentsy the stop-loss policy covering anything over $200,000.
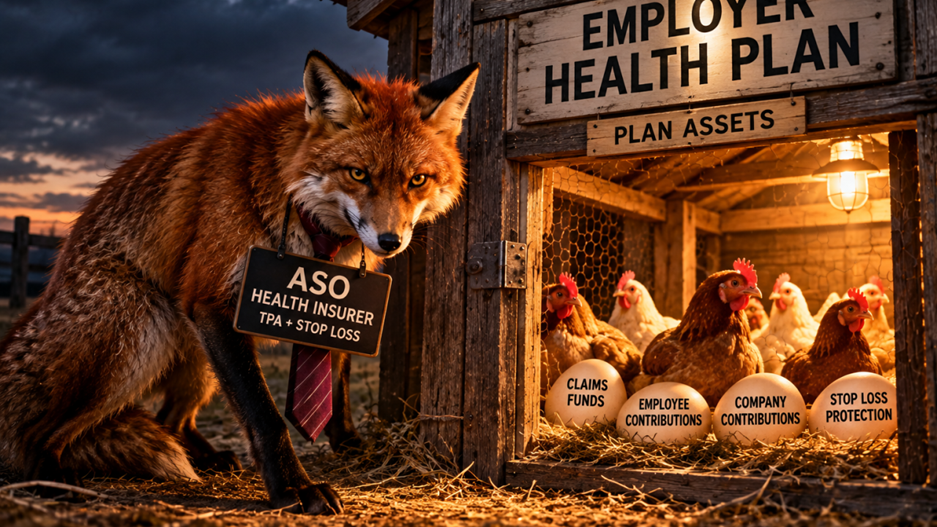
Certain conflicts in the healthcare system have become so commonplace that many stop noticing them. One of the most dangerous is the fully bundled healthcare plan. A self-funded employer hires a major carrier to provide the network and administer the health plan. That same carrier also sells the employer its medical stop-loss insurance. Institutional brokers pitch this as a streamlined ecosystem of integrated data. Then a seven-figure claim shows up, and you discover you have handed the keys to your self-funded henhouse directly to the fox who is financially incentivized to devour the flock.
When the organization responsible for processing a catastrophic claim is also the organization that must reimburse you when the claim crosses the specific deductible, you have a potential problem. The September 3, 2026 federal court decision involving Scentsy and Blue Cross of Idaho chillingly illustrates what can happen when the referee is also the insurer.
The Scentsy Precedent
Scentsy sponsored a self-funded employee health benefit plan and hired Blue Cross of Idaho to act as both its claims administrator and its stop-loss insurer for claims exceeding $200,000. The conflict ignited over a newborn plan participant with severe birth defects. The infant required intensive care at an out-of-state hospital, generating approximately $987,000 in one block of claims and another $1.4 million in subsequent claims.
The carrier processed and covered the first large claim under the stop-loss policy. The second claim, however, met a different fate. Because the treatment occurred in California, the claim moved through the Blue Cross inter-plan system. Blue Shield of California served as the host responsible for dealing with the hospital. This second massive claim did not officially reach the Idaho carrier until September, and they delayed processing it until three months after the stop-loss contractual period expired. Consequently, the carrier refused to reimburse the employer for the excess loss. Scentsy was left holding the entire $1.4 million bill.
Think about the mechanics of that arrangement. The later the claim was paid, the better the financial result for Blue Cross of Idaho.
ERISA Does Not Ignore the Conflict
Scentsy rightfully sued, and the federal district court did not ignore the obvious structural conflict. ERISA fiduciaries owe an undivided duty of loyalty to plan participants and must act as though they are entirely free of competing financial motives.
The carrier argued that their complex network arrangements absolved them of responsibility for the out-of-state processing delays. They claimed they lacked authority over the local host processing the claim. The court rejected this defense completely. ERISA strictly prohibits any agreement that purports to relieve a fiduciary of its legal duties. Internal procedures and administrative complexity do not excuse a fiduciary from protecting the plan.
More importantly, the carrier argued it could not be responsible for failing to pay a claim it technically had not yet received. But the carrier already knew about the high-cost claimant. Months before the stop-loss deadline, they had identified the infant’s serious medical conditions and knew she was generating an excess loss claim. Because the carrier possessed that knowledge while harboring a financial conflict, the court ruled they had an affirmative fiduciary duty to expedite the processing to protect the plan from a lapse in coverage. Because they blatantly ignored this duty, the court granted equitable relief in the form of a surcharge to prevent the carrier from enjoying unjust enrichment.
Specifically, about such bundled ASO arrangements, the court said:
Because BCI [Blue Cross of Idaho] is both the claims administrator for excess loss claims under the ASA and it covers those claims under the ELC, it faces a conflict of interest anytime there is an excess loss claim. BCI had an actual conflict of interest because it owed fiduciary duties to administer the second excess claim and a contractual obligation to cover that claim.
The Underwriting Reality
The practical lesson for employers extends far beyond the courtroom. This scenario is a recurring feature of a deeply broken system. When you bundle your claims administration and your stop loss, you create an environment where high-dollar claims can conveniently fall through the cracks during the transition between policy years.
We see this reality play out constantly when evaluating the market. Independent stop-loss carriers are extremely skeptical of these bundled arrangements. When they quote new business, their underwriters scrutinize the data for this exact fact pattern. They know incumbent carrier combinations often let complex claims bleed over the contract deadline. The incoming market refuses to be held responsible for the prior carrier’s intentional administrative lag.
The outgoing stop loss carrier will say the claim was paid too late. The incoming carrier will apply a laser or exclude the claim entirely. The employer is left sitting in the middle, forced to write a seven-figure check.
Convenience is Not Risk Management
You absolutely cannot rely on brokers whose default strategy is to bundle your stop loss with one carrier and one third-party administrator. Their laziness or lack of sophistication is leading you into a structural trap designed to protect the profit margins of the carrier, not the assets of your organization. A simplified set of negotiations with one entity (an insurer) instead of a separate TPA, stop-loss insurer, and network or repricer is not a substitute for rigorous risk management.
The strategic imperative to protect your self-funded plan is unbundling. Carving out the excess loss coverage from the administrative services removes the inherent friction. A completely independent third-party administrator has absolutely no competing financial motive to drag out the processing of a million-dollar hospital claim. Their sole mandate is to process the claim efficiently, which in turn triggers the independent stop-loss reimbursement precisely when it should be triggered.
There must be a reasoned decision about who administers claims, who holds the catastrophic risk, and exactly who is responsible when a claim is caught between policy years. Demand total transparency, reject the bundled illusions pitched by conflicted brokers, and take back control of your fiduciary responsibilities.