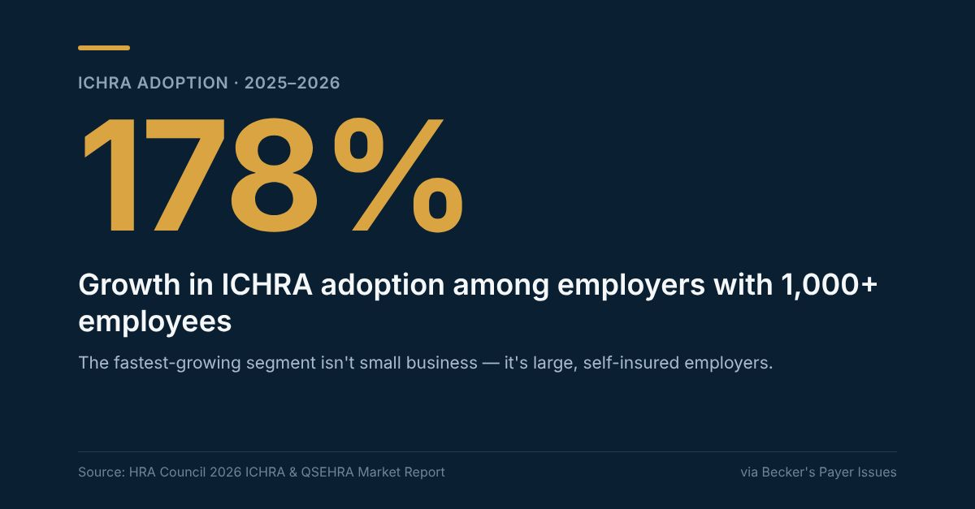
“Except the fastest-growing segment is employers with 1,000+ employees. Adoption there is up 178%. These aren’t businesses with no benefits history. These are companies that ran full group plans for years and decided a defined-contribution individual model is the better buy.”
By Bob Alber
The ICHRA numbers just came out, and the growth isn’t where I expected.
Covered lives roughly doubled to 500K+ this year. Normal story so far — ICHRA was built for small employers who couldn’t afford group coverage to finally offer something.
That’s the part worth sitting with if you sell individual product. The buyer walking in from a 1,000-life ICHRA employer isn’t a price-sensitive subsidy shopper. Median employer allowance is $459/month, and most of them top it up out of pocket. They expect group-plan service levels on an exchange product.
Carriers still pricing and servicing that segment like a subsidized marketplace shopper are going to lose that book to whoever builds for it on purpose.
Where are you seeing ICHRA show up in your book this renewal season — broker conversations, RFPs, or neither yet?